Opportunity
A Strategic Supply Chain Bottleneck
Today, China controls approximately:
global rare earth production
refining capacity
magnet manufacturing capacity
This concentration creates significant vulnerabilities for global manufacturers and governments.
Why It Matters
NdFeB magnets are the strongest commercially available permanent magnets and are indispensable to electrification and automation. The key demand drivers include:

Electric Vehicles
Traction motors and auxiliary systems. A single EV drivetrain requires up to 1 kg of rare earths.
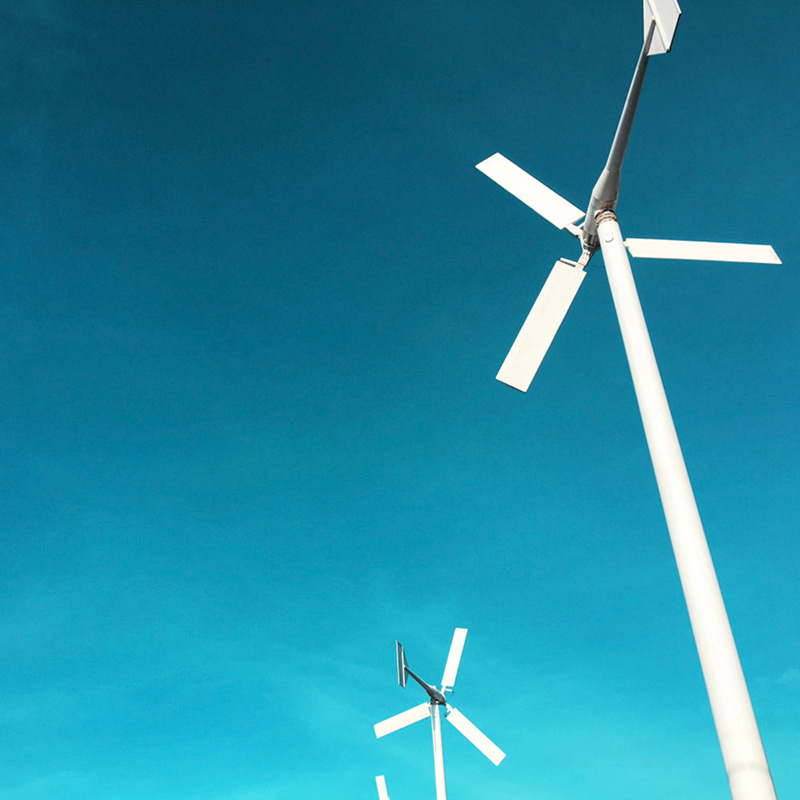
Wind Energy
Wind turbines utilize massive direct-drive generators reliant on magnets
Aerospace
Critical guidance systems, actuators, communications, drones, and industrial robotics depend on the high magnetic strength that can withstand high temperatures.
Industrial Robotics & Automation
Precision motors and sensors require high strength permanent magnets.
Consumer Electronics
Smartphones, laptops, and audio devices.
Healthcare and public health sector
Open MRI machines and other medical equipment.
North America Challenges
Structural Supply Chain Imbalance
The global rare earth value chain is currently concentrated in a small number of regions, with the majority of refining capacity and permanent magnet production located outside North America, even though raw material mining is more geographically distributed. The U.S. holds substantial geological reserves but has not yet built out commercial-scale midstream and downstream processing capacity, creating a gap between domestic resource potential and domestic industrial capability.
Market Volatility & Supply Continuity
Global rare earth supply has historically been subject to shifting export policies, licensing requirements, and pricing dynamics across producing regions. This dynamic introduces uncertainty for manufacturers seeking stable, long-term access to magnet materials — particularly OEMs in EVs, wind turbines, and robotics — and underscores the value of diversified, regionally distributed supply options.
Policy-Driven Demand & Capital Alignment
The U.S. government has committed substantial capital and regulatory support to rebuild a domestic “mine-to-magnet” supply chain:
Inflation Reduction Act (IRA)
Tax incentives tied to domestic and allied sourcing of critical materials.
Qualifying Advanced Energy Project Credit (48C) Program
Offer tax credits for investments in critical materials projects.
The Manufacturing Capability Expansion and Investment Program (MCEIP)
A five-year rare earth investment strategy to build “mine-to-magnet” domestic capacity at all critical nodes of the rare earth supply chain. Those critical nodes include sourcing, separation, processing, metallization, alloying, and magnet manufacturing.
Small Business Investment Act of 1958 (SBIC Program)
New rules allow SBICs investing in critical technologies and mineral extraction/conversion/processing to enhance supply chain resilience.
Bipartisan Infrastructure Law (BIL)
Direct investment in supply-chain manufacturing assets
This policy framework creates durable demand visibility, non-dilutive capital opportunities, and accelerated customer adoption for qualified domestic producers.
Additionally, U.S legislation has proposed the adoption of The Rare Earth Magnet Manufacturing Production Tax Credit Act, offering a tax credit for domestic production of rare earth magnets.
In February 2026, the U.S. announced a “tariff floor” policy to protect domestic producers from price manipulation, contributing to heightened market volatility. The U.S. has also established import tariff rates on rare earth metals, oxides, and carbonates.
